Short answer: The cash flow management strategies that work for a Dallas small business are simple to name and hard to keep up: forecast cash weekly, invoice the day the work is done, chase receivables on a schedule, line up payment terms, plan for taxes, and hold a reserve. Each one rests on books reconciled every month, so you know what cash you really have and where it went.
Key takeaways
- Profit is not cash: late payments, loan principal, owner draws and tax payments all drain cash without touching profit.
- The fastest wins are usually in collections: invoice the same day and follow up on a fixed schedule.
- Set aside money for taxes every month; the IRS allows estimated payments weekly or monthly.
- A weekly forecast shows a shortfall weeks ahead; a monthly report shows it after it happened.
- None of these techniques work on books that are months behind.
What cash flow management means for a small business
Cash flow management is the habit of knowing, ahead of time, how much money will come into the business and go out of it, and acting before the bank balance forces a decision. It is not the same as profit. Your Profit & Loss can show a good month while the account runs low, because profit counts work billed and cash counts money collected.
The gap between the two has ordinary causes: customers paying on 30- or 60-day terms, loan principal (which is not an expense), owner draws, inventory bought before it sells, and sales tax collected for the state that has to be paid over. Our article on why a profitable business can be short on cash walks through a worked example.
The 10 cash flow management strategies at a glance
These are the cash flow management techniques we see make the biggest difference for established service businesses in Dallas–Fort Worth. The table shows each strategy, the first step, and the report that tells you it is working.
| Strategy | First step | Report that shows it works |
|---|---|---|
| 1. Forecast cash | List expected receipts and payments by week for the next 13 weeks | Cash forecast vs. actual bank balance |
| 2. Invoice faster | Send the invoice the day the work is finished | Days from job completion to invoice |
| 3. Track receivables | Review the aging report every week | Accounts receivable aging |
| 4. Cut extra spending | Review every recurring charge and subscription | Profit & Loss compared month to month |
| 5. Manage inventory | Set reorder points for items you stock | Inventory on hand vs. monthly usage |
| 6. Negotiate payment terms | Match supplier terms to the terms you give customers | Accounts payable aging |
| 7. Plan for taxes | Move a set share of each month’s profit to a tax account | Tax account balance vs. estimated tax due |
| 8. Review cash monthly | Read the Statement of Cash Flows after each close | Statement of Cash Flows |
| 9. Use the right tools | Connect bank feeds and online payments to your accounting system | Unreconciled items at month-end |
| 10. Build a cash reserve | Set a minimum balance and transfer toward it monthly | Reserve balance vs. your target |
How to read this table: start with the strategies whose report you do not get today. If nobody sends you a receivables aging or a Statement of Cash Flows each month, that missing report is your first fix, because you cannot manage what you cannot see.
Strategies 1 to 3: see cash coming and collect it faster
1. Predict your cash flow
A cash flow forecast starts from today’s bank balance, adds expected collections and subtracts payroll, rent, vendor bills, loan payments, taxes and owner draws, week by week. The week the ending balance drops below your minimum is the week to act on, while there is still time to collect, delay a purchase or arrange credit. Our guide to the 13-week cash flow forecast shows the layout with an example.
2. Get paid faster
Every day between finishing a job and sending the invoice is a day added to your wait for cash. Send invoices the same day, state the due date and the payment methods on the invoice, and accept online payments so the customer can pay from the email. Clear terms, such as “due in 15 days,” prevent most disputes about timing.
3. Keep an eye on money owed to you
Run the accounts receivable aging report every week and work it from the oldest balance down. A simple follow-up schedule works for most service businesses: a reminder a few days before the due date, a call or email on the day it becomes late, and a firmer step at 30 days. Customers who are always late are a pricing and terms question, not only a collections one.
Strategies 4 to 6: spend, stock and pay on your terms
4. Cut down on extra spending
Go through every recurring charge on the bank and card statements: software, subscriptions, memberships, services billed automatically. Compare each expense line with the same month last year. Lines that grew faster than revenue are where to look first.
5. Manage your inventory wisely
Inventory is cash sitting on a shelf. If you stock materials or products, set reorder points based on how fast items actually move, count regularly, and avoid buying in bulk unless the discount is worth more than the cash it ties up.
6. Negotiate better payment terms
If you pay suppliers in 10 days and customers pay you in 45, you are financing your customers. Ask suppliers for terms closer to the ones you give, ask larger customers for deposits or progress billing on long jobs, and keep both on paper. The accounts payable aging report shows what you owe and when, so you pay on time without paying early by habit.
Strategy 7: plan for tax payments
Taxes are the outflow owners most often forget to plan for. Texas has no state personal income tax, but federal income tax on business profit still has to be paid during the year through estimated payments, and many Texas businesses also owe a franchise tax report each May and collect sales tax that belongs to the state, not to the business.
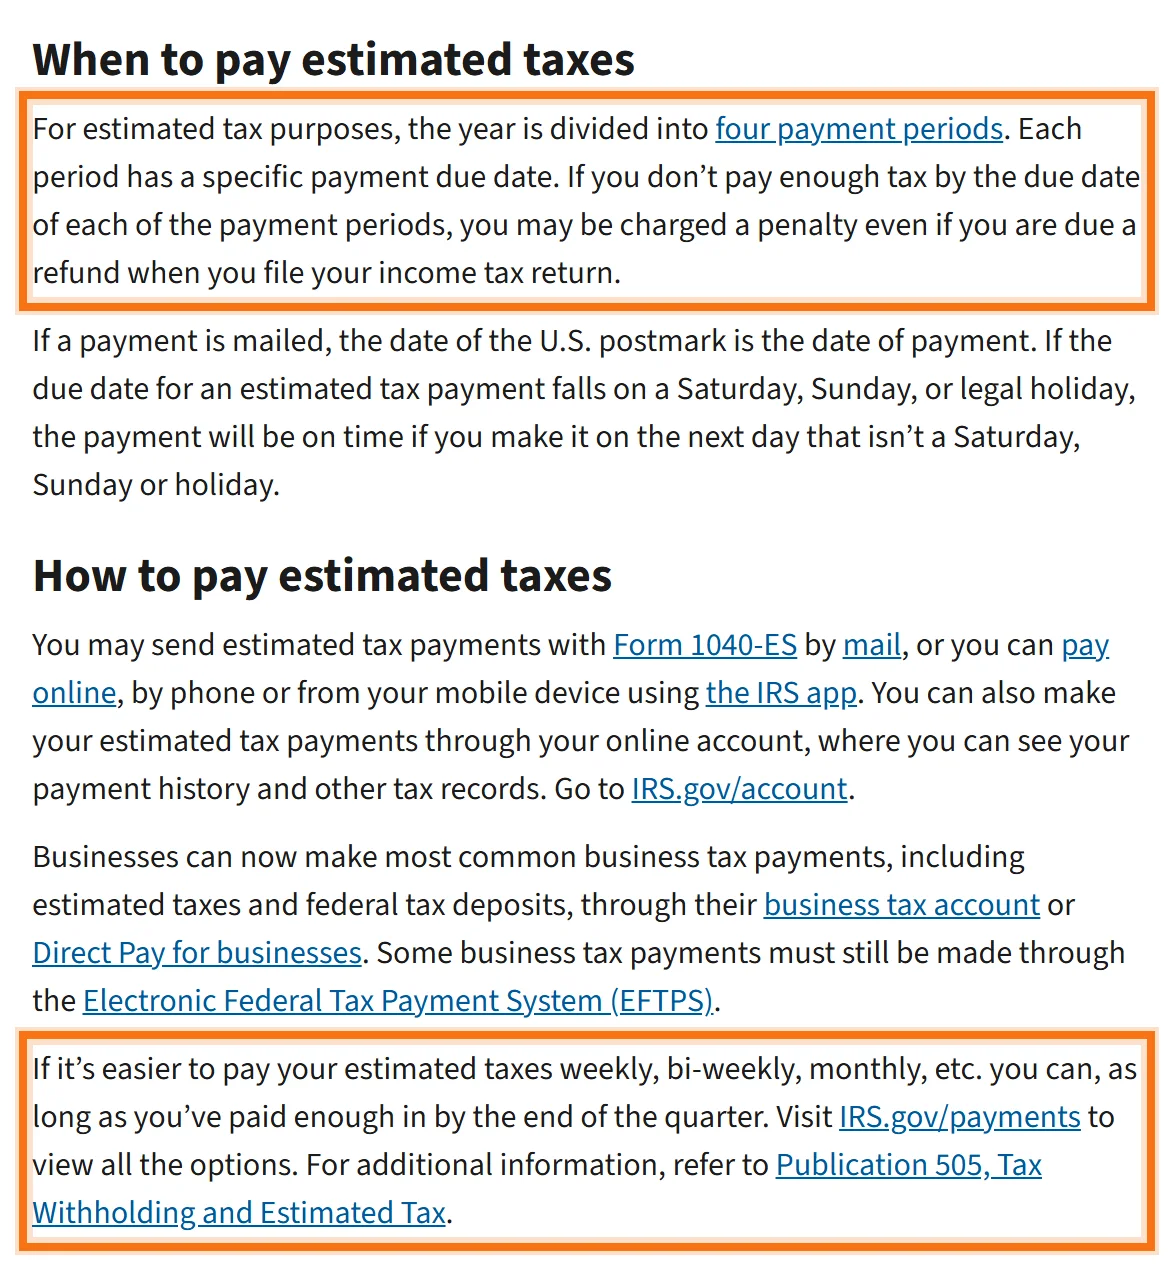
The practical fix is a separate tax savings account. Each month, after the books are closed, move a set share of the month’s profit into it, and pay estimated taxes from that account. Your CPA can tell you the right share for your situation; your bookkeeper makes sure the profit figure it is based on is right.
Strategies 8 to 10: review, automate and build a cushion
8. Check your cash flow regularly
Look at the bank balance and receivables weekly, and read the Statement of Cash Flows every month once the books are closed. That statement explains why cash moved: operations, investments such as equipment, or financing such as loan payments and owner draws. Our guide to the monthly financial reports your bookkeeper should send covers what a complete package includes.
9. Use technology to manage cash flow
Bank feeds, online invoicing and payment links in QuickBooks Online or similar software remove most manual entry and shorten the time between work done and cash received. Software does not replace review: someone still has to reconcile every account each month so the numbers you plan from are correct.
10. Build a cash cushion
Decide on a minimum balance, such as a set number of weeks of payroll, rent and loan payments, and transfer toward it every month until you reach it. A reserve turns a slow month or a late customer into an inconvenience instead of an emergency.
When to get cash flow help in Dallas
Most owners can run the first few strategies themselves. Help pays for itself when the books are behind, when profit and cash keep telling different stories, or when a big decision, such as a hire, a loan or a second location, depends on knowing the low point in your cash months ahead.
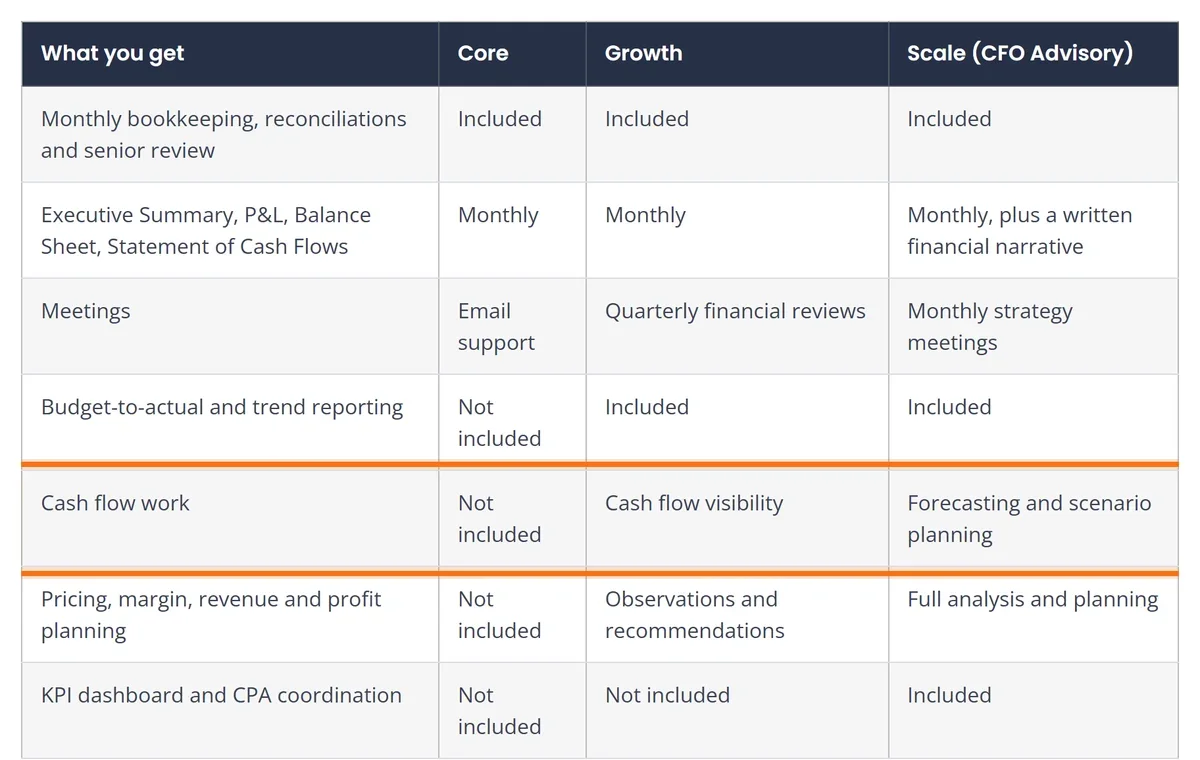
LUCI Financial Solutions is a Dallas–Fort Worth bookkeeping and financial operations firm for established service businesses, typically those earning $250K or more a year. Every client starts with Core: transactions categorized in QuickBooks Online, every account reconciled, a senior review and a monthly package with a Statement of Cash Flows. Growth adds cash flow visibility and trend reporting with quarterly reviews; Scale (CFO Advisory) adds cash flow forecasting and scenario planning with monthly strategy meetings. See bookkeeping services in Dallas or fractional CFO services in Dallas.
Frequently asked questions about cash flow management
What are the best cash flow management strategies for a small business?
Forecast cash week by week, invoice the day work is done, follow up on receivables on a schedule, match payment terms with suppliers to the terms you give customers, set money aside for taxes every month, and keep a cash reserve. All of them depend on books that are reconciled every month.
What is the difference between profit and cash flow?
Profit is revenue minus expenses for a period. Cash flow is the money that actually came in and went out. A business can show a profit while cash falls, for example when customers pay late, loan principal is repaid or the owner takes distributions.
How much cash reserve should a small business keep?
There is no single rule. Many owners plan around a set number of weeks of fixed costs, such as payroll, rent and loan payments. A 13-week forecast shows the lowest point your cash reaches, which is a practical way to set the floor for your own business.
How often should I review cash flow?
Look at the bank balance and receivables weekly, and review the Statement of Cash Flows monthly once the books are closed. Businesses with tight months or seasonal swings benefit from a rolling 13-week forecast updated every week.
Which reports show cash flow problems early?
The accounts receivable aging report shows who is paying late, the Statement of Cash Flows shows where cash went last month, and a cash forecast shows the weeks ahead when cash may run short.
Does LUCI Financial Solutions help Dallas businesses with cash flow?
Yes. LUCI keeps the books for established Dallas–Fort Worth businesses every month with a senior review. The Growth tier adds cash flow visibility and trend reporting, and the Scale (CFO Advisory) tier adds cash flow forecasting and scenario planning.
Cash you can plan around
Reconciled, reviewed monthly books, a Statement of Cash Flows every month, and forecasting when you need it. See our bookkeeping services in Dallas.